property
KL Property in 2026: How This Market Stacks Up Against the 2021 Boom
Transaction volumes are climbing, prices in select corridors are testing post-pandemic highs, but the drivers this time around look fundamentally different.
How we reported this
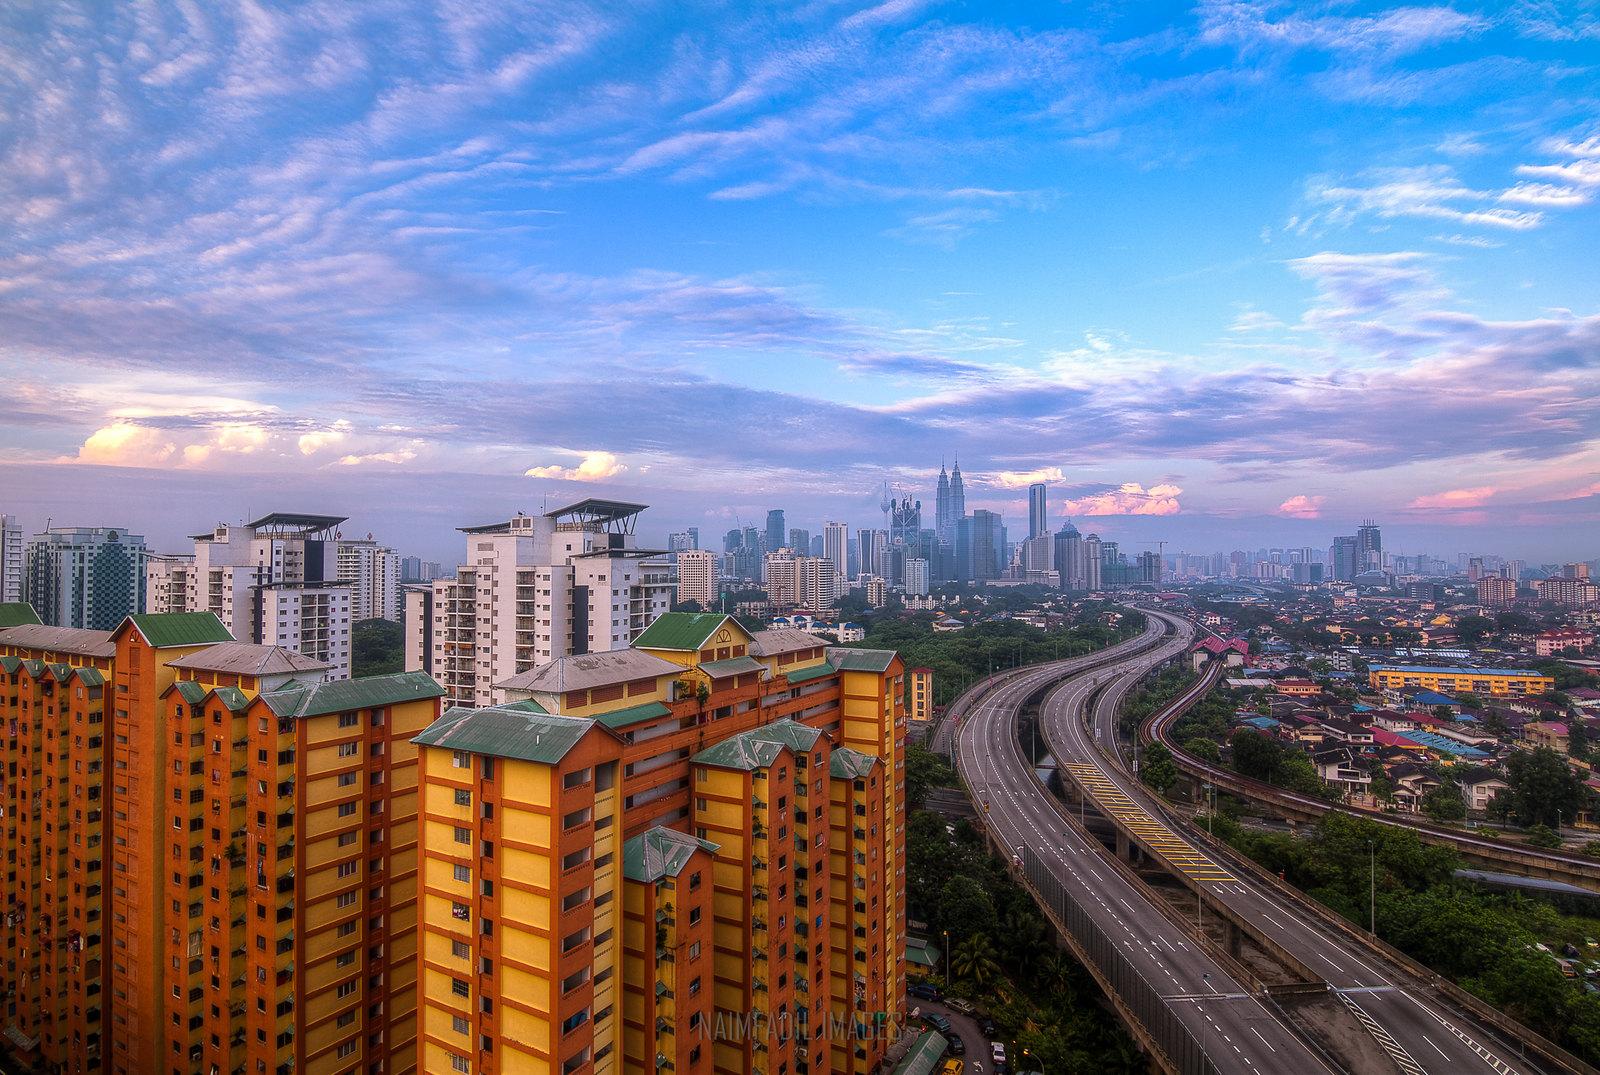
Kuala Lumpur's residential property market closed the first half of 2026 with its strongest six-month transaction count since the pandemic-era surge of 2021, according to data tracked by the National Property Information Centre (NAPIC). The uptick is sharpest in the Mont Kiara and Dutamas corridors, where asking prices for mid-to-high-tier condominiums have crept back above RM900 per square foot for the first time since that earlier cycle peaked.
The comparison to 2021 matters because that boom was largely artificial, a product of the Home Ownership Campaign (HOC), stamp duty waivers, and suppressed interest rates that pulled forward demand rather than created it. What analysts and agency heads are seeing in 2026 is a structurally different story, one built more on genuine end-user activity and foreign re-entry than on government incentive engineering.
Then Versus Now: What's Actually Moving Prices
In 2021, the HOC, which ran in various forms between 2019 and 2021, delivered stamp duty exemptions on properties up to RM2.5 million and helped push national residential transactions to a multi-year high. The Klang Valley captured a disproportionate share of that activity, with Chow Kit and Setapak recording unusual volume as buyers swept up affordable stock below the RM500,000 threshold to maximise exemption benefits. Prices moved, but they moved on subsidised demand, and when the HOC closed, parts of that market gave back ground quickly through 2022 and into early 2023.
The 2026 cycle has no equivalent blanket incentive propping it up. The main policy tailwind is the Madani Economy framework's ongoing push to attract high-value foreign talent and corporate relocation, which has fed occupier demand in Bangsar South, now formally rebranded as Nexus Bangsar South under ongoing placemaking efforts, and along the Jalan Ampang diplomatic and expatriate belt. Monthly rentals for three-bedroom units in Bangsar South's newer towers have risen to between RM5,500 and RM7,000 in the first half of this year, up from a range of roughly RM4,200 to RM5,500 in mid-2023, according to listings tracked by IQI Global Malaysia.
Foreign buyer activity, particularly from China and the Middle East, has also returned more visibly than at any point since Malaysia reopened its borders. The Malaysia My Second Home (MM2H) programme, restructured in late 2023 with lower financial thresholds than the punishing 2021 revision, has contributed to a measurable uptick in applications, though NAPIC and the Tourism Ministry have not yet published combined 2026 conversion data.
Where the Gaps, and the Risks, Still Are
Not every submarket is sharing equally in the momentum. The overhang of unsold serviced apartments, a problem that dogged KL through 2022 and 2023, has not fully cleared. Areas like Sri Petaling and parts of Kepong still carry above-average unsold inventory in the sub-RM600,000 band, a hangover from the HOC years when developers launched aggressively to capture exemption-driven buyers. NAPIC's overhang data from Q4 2025 put the national residential overhang at around 25,000 units, with Kuala Lumpur contributing a meaningful share of that total.
The interest rate environment is also meaningfully different from 2021's near-zero base. Bank Negara Malaysia's Overnight Policy Rate has been held at 3.00 percent since early 2024, compared to the historic low of 1.75 percent that prevailed through much of the 2021 buying frenzy. That 125-basis-point difference translates directly into higher monthly servicing costs, which acts as a natural ceiling on price appreciation for leveraged buyers.
For buyers and investors weighing entry right now, the practical read is this: the neighbourhoods with genuine rental income support, Bangsar South, Mont Kiara, the stretch around KL Sentral, have credible legs under their pricing. Speculation-heavy launches in peripheral locations without anchor infrastructure should be approached with far more caution than they were in 2021, when the HOC made almost any purchase look temporarily profitable on paper. The 2021 lesson, still fresh enough to sting, is that policy-driven spikes leave behind buyers who overpaid when the policy disappears.
This article is general information only and is not personal financial or investment advice. Consider your own circumstances and seek licensed professional advice before making financial decisions.